We had ended the first two months of 2017, let's see how 穷小子's portfolio performed.
穷小子 has not done anything to his portfolio in 2017 yet.
- Prices are not high enough to sell
- Prices are not low enough to buy
- More importantly is, 穷小子's pocket is still empty. Still building his warchest.
穷小子's portfolio update:
For the period of these first two months, 穷小子 will be receiving a total of S$812.82 of dividends. Slightly more than half of it is much contributed by the newly purchased REITs, feels that these are good purchases so far.
Watchlist
Looking at ComfortDelgro currently after reading some of the thoughts from some of the bloggers and forumers. While trying to wait for his salary and dividends to come in this week, ComfortDelgro had slowly creeping upwards day by day. Shall wait for an opportunity for a good price.
March US interest rates hike
The odds of an increase have jumped above 70 per cent, from 40 percent on Friday. If ComfortDelgro price doesn't comes down, then 穷小子 may change his direction to REITs again. Made quite a good purchases last December, looking to add more either MCT or FCT.
Ezra's joint venture files for bankruptcy. Will this become a domino effects which caused another sell-down on the banks again? As what had happened last year? 穷小子 don't know too, but it will be wise to save some money for banks shopping.
Year 2017
Total dividends: S$812.82
Average dividends per month: S$406.41
Average dividends per day: S$13.78
Showing posts with label review. Show all posts
Showing posts with label review. Show all posts
Wednesday, 1 March 2017

Wednesday, 18 January 2017
CapitaLand Commercial Trust (CCT) FY 2016 Financial Results
CCT released their FY 2016 Financial Results this morning. Seems a strong results for 2016 overall per se. 穷小子 shall touch on some of the key factors.
Starting off with the much anticipated on CapitaGreen contributions injections to the portfolio. Note that its contributions is 100% only from 01 Sep 2016 onwards, so expecting the 11% to grow continuously for its full contributions in FY 2017. This will be a good news for investors, and if remember correctly, CapitaGreen was funded internally by CCT, with no rights issued that time.
Portfolio was up by 13.6% YoY, and again mainly due to the increased stake in CapitaGreen.
Debt maturity are evenly spread for the next 6 years with 38% matured on FY 2020. Once again, S$890M (27%) are due to the increased stake in CapitaGreen.
CCT did measures to curb the interest rate hikes effects. Only 20% of the borrowings are on Floating Rate.
Despite oversupply of offices for past few years, CCT is able to consistently above market occupancy, ending the last quarter of 2016 with 97.1% against 95.8%.
Although there is a dipped of 0.2% in the last QoQ, it has been an impressive increasing for the past 17 quarters consecutively.
Well spread of portfolio lease expiry although with majority on 2019. 25% and 7% for Office and Retail respectively.
Every investors' favourite, including 穷小子 too. Income, Assets, DPU and NAV increasing consistently over the years. As Peter Lynch stated in "Beating the Street", "The dividend is such an important factor in the success of many stocks that you could hardly go wrong by making an entire portfolio of companies that have raised their dividends for 10 or 20 years in a row."
Sounds logical.
CCT's portfolio committed an impressive occupancy rate of above 90% consistently for the past 10 years. If omitted the 94.8% in 2009 which is due to Global Financial Crisis, technically speaking should above 95% consistently.
Maybe 穷小子 is bias and a bit of exaggerating in this review because this is the highest holdings REITs stock in his portfolio, but an impressive 10 years track records doesn't lies.
穷小子's concludes that this can be one of the "safe" stock for now until 2019 and 2020, the year which has the most portfolio lease expiry and the highest debt maturity amongst respectively. 穷小子 believes that the management will take necessary measures when the time are nearer.
 |
| CapitaGreen's contributions is 100% with effect from 01 Sep 2016 |
 |
| Portfolio up by 13.6% YoY |
 |
| Debt Maturity |
 |
| Borrowings |
 |
| Portfolio Occupancy rate |
 |
| Monthly average office rent |
 |
| WALE |
 |
| Consistently delivery value |
Sounds logical.
 |
| Consistently above 90% |
Maybe 穷小子 is bias and a bit of exaggerating in this review because this is the highest holdings REITs stock in his portfolio, but an impressive 10 years track records doesn't lies.
穷小子's concludes that this can be one of the "safe" stock for now until 2019 and 2020, the year which has the most portfolio lease expiry and the highest debt maturity amongst respectively. 穷小子 believes that the management will take necessary measures when the time are nearer.
Sunday, 8 January 2017
What a good start for 2017!!
What a good start for 2017!! STI from 2880.76 on the last day of 2016 to 2962.63 on the end of first week, that's almost a 100 points, roughly 2.84% increased, for a short 4 days. Can we see a STI 3000 by month end?
穷小子 shared about his Christmas Shopping previously, so how have they performed?
Capital Gains
Those REITs which bought on the last month of 2016, grew from a low of negative 2.54% to positive 2.68% averagely. Seems like a strong comeback of 5.22% within 2 weeks. Hmm. But REITs are meant for long-term anyway. Hehe~~
Dividend Yield
These 4 REITs return an average dividend yield of 5.87%. Aiming for a 6% average initially, but perhaps too impatient and afraid of missing the opportunities.
Assuming if the prices and dividend payouts are remain around this range for 2017, these 4 REITs may be able to return a total of about 8.55% this year. Capital Gain + Dividend Gain.
Shall accumulate and re-balance the portfolio if rate hikes again. Is this so called a 把危机转变为商机? Shall revisit this post again by end of 2017.
Lets see how the second week of 2017 performs.
Thursday, 22 December 2016
Christmas Shopping
穷小子 is having his festive seasons shopping for the past few weeks. Shopping for gifts for friends, families, and self. Mainly being to Raffles City, Bugis, Vivocity, Waterway Point, Suntec. Managed to get a perfect gift for everyone, and with much shopping malls rewards points accumulations as well as credit cards rebates. Most importantly, 穷小子 had bought most of the REITS from his watchlists too. Yay! Interest rate hikes was over for this year, but do anticipate to have three rate hikes in 2017 with Fed's projection.
CapitaLand Mall Trust
CapitaLand has always been one of 穷小子's favourite shopping organisations. CapitaLand Mall Trust has 16 properties leading famously with Bugis, Plaza Singapura and Raffles City. This is in the top of 穷小子's target list. Snap it impatiently with slightly above book value immediately after the rate hikes news last week. The price had dropped about 1.8% after since, but nonetheless, 穷小子 is comfortable with the 5.77% yield. Looking out for this if it drops more. On side note, CapitaLand is 穷小子's first stock after all, long time supporter.
Mapletree Commercial Trust
穷小子 must admit that this was never in his watchlist until recently. 穷小子 went Vivocity to shop for the presents and notice that the crowd was overwhelming. Not that we didn't know that it is popular, but the crowd was still impressive every time 穷小子 visited it, and even after 10 years of operation. Vivocity holds a significant position in the southern part of Singapore. It is a bottleneck passage towards Sentosa, one of Singapore's iconic tourist attractions. Every visitors would need to pass through Vivocity to get into Sentosa, either by the Sentosa Express or by walking. If one would want to have a cheaper decent meal out from Sentosa, the nearest will be Vivocity.
On top of all these, there is Harbourfront Ferry Terminal which is just right next to it. Another group of crowd formed by tourists and locals who want to get into Batam or cruise.
Vivocity, Singapore's largest mall, will never be lacking of crowds with all these strategic advantages.
Another plus point is the diversification of Mapletree Commercial Trust. It has 5 properties only, but ranging from retail, to CBD offices, business park. On the downside, 穷小子 had paid about 6% premium to its book value for this. Will not be adding any more unless the next purchase is below its book value.
Fraser Centrepoint Trust
It comprises six suburban malls, Causeway Point, Northpoint, Changi City Point, Bedok Point, YewTee Point and Anchorpoint. 穷小子 had not personally visited any of these in the past weeks yet, but mainly inspired by The Centrepoint and Waterway Point, both which are under its parent's flagship. Likes with the new Centrepoint, a more open-concept layout with more F&B outlets after its renovations. Yes, Punggol Waterway point again, as blogged previously. Pinning on hopes that Fraser Management will inject Waterway point into Fraser Centrepoint Trust, to become the seventh "Point". Comfortably with about 6.2% yield and paid slightly lower than its book value.
Suntec Reit
Suntec City used to live in a shadow behind Raffles City and Marina Square, because of its accessibility disadvantages, losing out to both malls which are nearer to City Hall Station. The game had changed ever since the opening of Circle Line, and also with the completion of its renovations.
One of Promenade Station's exit is just right in front of Tower 3 entrance. Another would be Esplanade Station which is pretty close to the Convention Tower. 穷小子's observations is that the 2 stations' exits are bringing more crowd nowadays, more than City Hall's. Suntec is making good use of its good strategic location, and with the conventions halls filled with events all year round.
Did a small purchase last month before the rate hikes, but the price never come back ever since. Didn't add any more new positions this time round, but this definitely still within 穷小子's top reits target.
Glad that had "ate" some last month, so not in hurry to "eat" again.
CapitaLand Commercial Trust
Had reduced 40% of CapitaLand Commercial Trust about 3 months ago, after it had a great run to $1.64. 穷小子 is definitely happy to have it back before end of the year. Of course didn't get it back at the $1.45 low last month, due to too much fear about the rate hikes. Do not time the market. Haha.. Anyway, at 5.8% yield with about 15% discount to its book value is good enough for now.
With all the REITs purchased, 穷小子 shall close shop for this year. Let's see how the market react to the new year ahead. Total REITs' holding is at about 33% of the whole portfolio currently. Will be more mindful for any more REITs increase as 穷小子 don't wish REITs to be over-weighted.
Merry Christmas and a Happy New Year!!
Wednesday, 19 October 2016
M1 Third Quarter 2016 Results
M1 share price plunged 5.15% today, a $0.12 drop, to $2.21 today. This is much expected from the poor 3Q16 results released yesterday.
穷小子 mentioned in the previous post that M1 is having a juicy dividend yield of 6.38%, but because of fourth telco is approaching, patience prevails, and still waiting at the sidelines. Take a quick look on the 3Q2016 results.
Key Financial Highlights
穷小子 mentioned in the previous post that M1 is having a juicy dividend yield of 6.38%, but because of fourth telco is approaching, patience prevails, and still waiting at the sidelines. Take a quick look on the 3Q2016 results.
Key Financial Highlights
 |
| Operating Revenue $277.6m to $249.1m, -10.3% |
 |
| Cost of sales for 9 months $380.9m to $294.6m, -22.7% |
 |
| Net Profit after tax $44.9m to $34.4m, -23.4% |
 |
Cash & Cash equivalents, -62.9%
Net debt. 20.5%
Net debt/EBITDA, 24.8%
EPS, -12.0%
All these financial leverage are statistically bad.
|
Enough of the current statistic facts, let's see the good side of it.
As we all have known, majority of Singapore's consumers are bounded by the traditional 2 years contracts. Hence, the customer base is one of the most important factors to estimate the future, which at least how 穷小子 think.
Key Performance
Well, at least its 2 main business pillars', mobile and fixed services, base are increasing, at least at a slow pace.
Conclusion
Based on today closed price, the yield is about 6.9%, but of course, pretty much expecting a heavy cut to the dividends. Cut by how much is the big question for a dividend stock.
The management outlook are estimating a decline in FY2016 net profit after tax to be around the year-to-date range.
Assuming there will be a drop of 16% in EPS for FY2016, and the payout policy remains at 80%, we may be having a dividend of 12.8 cents for the next FY.
穷小子 is expecting few bad news to happen which can really hurt M1's share price deeply.
- News of fourth telco
- FY2016 results
- Cut in dividend
- Finally the completion of fourth telco (depending)
Hence not intending to average down in the near future. The first step which 穷小子 will be taking would be either wait for the price to hit at least $2.00 (psychological level), or after the fourth telco decision announced. Depends on whichever earlier.
As we all have known, majority of Singapore's consumers are bounded by the traditional 2 years contracts. Hence, the customer base is one of the most important factors to estimate the future, which at least how 穷小子 think.
Key Performance
 |
| Mobile Customer base |
 |
| Mobile Market Share |
 |
| Fixed services Customer base |
Conclusion
Based on today closed price, the yield is about 6.9%, but of course, pretty much expecting a heavy cut to the dividends. Cut by how much is the big question for a dividend stock.
The management outlook are estimating a decline in FY2016 net profit after tax to be around the year-to-date range.
Assuming there will be a drop of 16% in EPS for FY2016, and the payout policy remains at 80%, we may be having a dividend of 12.8 cents for the next FY.
穷小子 is expecting few bad news to happen which can really hurt M1's share price deeply.
- News of fourth telco
- FY2016 results
- Cut in dividend
- Finally the completion of fourth telco (depending)
Hence not intending to average down in the near future. The first step which 穷小子 will be taking would be either wait for the price to hit at least $2.00 (psychological level), or after the fourth telco decision announced. Depends on whichever earlier.
Lastly, bear in mind that the worst fearful concern is that, there is still no confirmation about a fourth telco yet, there is not even a first step made by the fourth telco, but M1 profits is already dropped hard. Imagine what can this fourth telco do more hurting if it realised.
P.S. 穷小子 is not spreading fear here. M1 is about 10.9% of his total portfolio now.
P.S. 穷小子 is not spreading fear here. M1 is about 10.9% of his total portfolio now.
Tuesday, 4 October 2016
What to do during this period?
What to do during this period?
Ever since the epic Brexit event, STI finally surged above 2,900 points to 2,945 unexpectedly, before coming down to 2,803 in the following month. Subsequently, it has been ranged bound between 2,800 and 2,900.
Those banks, telcos and REITs stocks in 穷小子's watchlists did not have much movements during this period as well. The announcement of delaying the rates hike in September didn't have much impact on the market at all, perhaps all are well within investors' expectations.
The price at current level is not high enough for 穷小子 to take profits, nor low enough for 穷小子 to add more positions. No dividends for September and October. Honestly speaking, this is boring, and 穷小子 did not pay much attention to the market during this period too.
All these may actually become a good time for investors to take a breath and do a review
穷小子 did the following:
After doing all these, the forecast for next year's dividend yield is pathetic, at a low range of 4%. Seems that telcos and REITs valuations could be more attractive now in order to increase the yield. Especially with M1 at a dividend yield of 6.38% on today's closing price, it could be an eye-catching.
Nonetheless, we must not forget that IDA is gonna make announcements regarding to fourth telco by the end of October, and rates hikes' decision will be made in December. These are the two major factors which will affect these two sectors respectively. Lastly, the much anticipated US President election will be around the corner as well in November.
Apart from all these, STI may continue to stagnant awhile, for at least after Chinese New Year which is Jan next year. Furthermore, the dividend seasons are pretty much over for this year.
These are all the reasons which why 穷小子 has not made his purchased yet. Patience ^^
穷小子 is almost 85% invested, hence this may be his last shot for any good bargains in the market.

Ever since the epic Brexit event, STI finally surged above 2,900 points to 2,945 unexpectedly, before coming down to 2,803 in the following month. Subsequently, it has been ranged bound between 2,800 and 2,900.
Those banks, telcos and REITs stocks in 穷小子's watchlists did not have much movements during this period as well. The announcement of delaying the rates hike in September didn't have much impact on the market at all, perhaps all are well within investors' expectations.
The price at current level is not high enough for 穷小子 to take profits, nor low enough for 穷小子 to add more positions. No dividends for September and October. Honestly speaking, this is boring, and 穷小子 did not pay much attention to the market during this period too.
All these may actually become a good time for investors to take a breath and do a review
穷小子 did the following:
- Re-valuate the valuations of those stocks in the watchlists.
- Based on the valuations, set the price alerts for each of them.
- Forecast dividend's yield and set targets for next year
After doing all these, the forecast for next year's dividend yield is pathetic, at a low range of 4%. Seems that telcos and REITs valuations could be more attractive now in order to increase the yield. Especially with M1 at a dividend yield of 6.38% on today's closing price, it could be an eye-catching.
Nonetheless, we must not forget that IDA is gonna make announcements regarding to fourth telco by the end of October, and rates hikes' decision will be made in December. These are the two major factors which will affect these two sectors respectively. Lastly, the much anticipated US President election will be around the corner as well in November.
Apart from all these, STI may continue to stagnant awhile, for at least after Chinese New Year which is Jan next year. Furthermore, the dividend seasons are pretty much over for this year.
These are all the reasons which why 穷小子 has not made his purchased yet. Patience ^^
穷小子 is almost 85% invested, hence this may be his last shot for any good bargains in the market.

Wednesday, 3 August 2016
OCBC 2Q2016 Financial Results
To be a better value investor, first of all, should at least know how to analyst a financial results.
As mentioned in all the previous posts, 穷小子 admitted that he is not a great Financial Analyst. Decided to do a simple analyst and shall use OCBC's first half of the year results for a start, since OCBC took up a majority of 穷小子's portfolio. Please advise/correct him there is any misinformation. Thanks.
 Believed that most of the broker's research reports and fellow bloggers should have covered pretty much already. Hence, shall not covers too much about the details, but only touch on the areas which 穷小子 is more concern about instead.
News headlines would says "Net profit of S$885m was 15% lower YoY; but 4% higher QoQ". Most of the news says it is drag down by its insurance arm, Great Easter's earnings. Actually why is it so? Is it good or bad? 穷小子 do not have a definite answer for now, perhaps need to wait for the annual report to see if there is any improvement before suggesting further.
Next is we need to know how much is OCBC's insurance arm's weightage.
Next up to the concern in trend would be the Oil and Gas exposure.
Total exposure to Oil and Gas is S$14.3b, and out of which, the customer loans is only at 6%. If 穷小子 remember correctly, the CEO did says that this is negligible during the last AGM. At least there is no exposure to Swiber.
If only to put UK into account, it is only about 2.2% of total assets, which is negligible as well.
Was expecting to have a better payout ratio of at least 40% and a higher dividend at about $0.37-$0.38 for last year, but too bad. Well, at least they did increase the payout ratio for this time round, and didn't cut the dividend. Give and take for this.
Another disappointing factor is that there is no scrip dividend for this time round, although did mentioned that this is up to the management decision.
Assuming based on today's XD closing price at $8.35, a rough calculation would means that the scrip price should be at least below the current book value. 穷小子 always loves the scrip dividend when the price is low.
Conclusion
It seems that only Great Eastern's profits contribution is the only one which signal the minor red flag here. Both Oil & Gas and Brexit concerns can be negligible. No changes to the strategy, will continue to hold this for a very long term, and in fact, looking at an opportunity to buy when the price is 0.90x of the book value.
As mentioned in all the previous posts, 穷小子 admitted that he is not a great Financial Analyst. Decided to do a simple analyst and shall use OCBC's first half of the year results for a start, since OCBC took up a majority of 穷小子's portfolio. Please advise/correct him there is any misinformation. Thanks.

News headlines would says "Net profit of S$885m was 15% lower YoY; but 4% higher QoQ". Most of the news says it is drag down by its insurance arm, Great Easter's earnings. Actually why is it so? Is it good or bad? 穷小子 do not have a definite answer for now, perhaps need to wait for the annual report to see if there is any improvement before suggesting further.
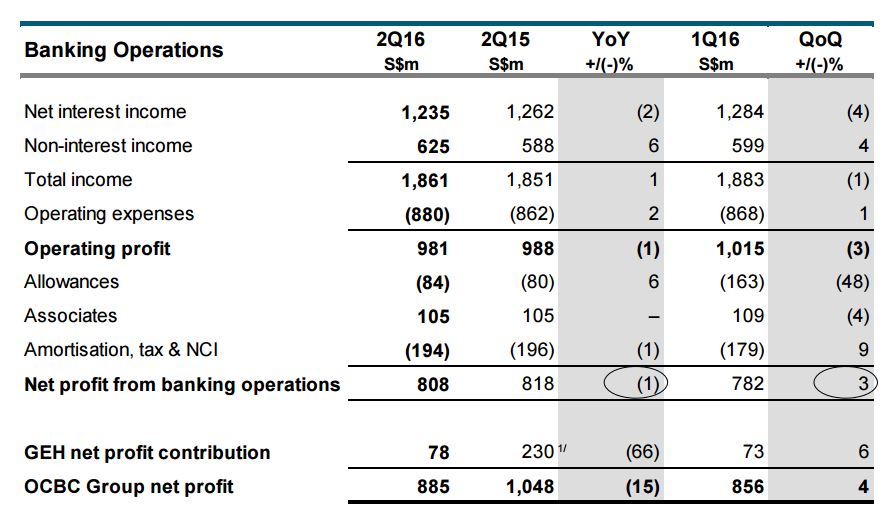 |
| We can see that there is a great drop of 66% in Great Eastern profits contribution from last year. Shall not covers more about why Great Eastern profits drop since the concern here is about OCBC. |
Next is we need to know how much is OCBC's insurance arm's weightage.
 |
| Insurance's weight at about 11% |
To 穷小子's simplest way of understand is that 11% of OCBC value will be totally wiped off if only there is a worst case scenario for Great Eastern. Guess that OCBC should be able to survive it, but of course, we are still far from seeing this to happen.
Next up to the concern in trend would be the Oil and Gas exposure.
 |
| 6% of total customer loans |
Coming up next will be the exposure to the Brexit effects.
 |
| Less than 3% of total assets |
Last but not least, let's look into the what 穷小子 interest in most, the dividend payout.
 |
| Maintained dividend of $0.18 per share |
Another disappointing factor is that there is no scrip dividend for this time round, although did mentioned that this is up to the management decision.
Assuming based on today's XD closing price at $8.35, a rough calculation would means that the scrip price should be at least below the current book value. 穷小子 always loves the scrip dividend when the price is low.
Conclusion
It seems that only Great Eastern's profits contribution is the only one which signal the minor red flag here. Both Oil & Gas and Brexit concerns can be negligible. No changes to the strategy, will continue to hold this for a very long term, and in fact, looking at an opportunity to buy when the price is 0.90x of the book value.
Thursday, 7 July 2016
Was it a right choice to sold off Noble?
A recapped, about a month after the sold off, and about a week after it XR. Have sold off Noble shares on 03 Jun 2016. Let's see whether did 穷小子 had made the right choices so far.
From the price at $0.26 on 03 Jun 2016, to the closed price at $0.215 on 27 Jun 2016 (the day before XR). It is about a drop of 17.3%.
Based on the formula, and with the rights issued price of $0.11, the theoretical price should be $0.1625. Due to whatever the reasons, it closed at $0.18 on the 28 Jun 2016 (the XR date) which is higher than the theoretical price.
The mother share closed at $0.184 today, 07 July, and with Noble R share closed at 0.074.
穷小子 sold his 3,000 shares on 03 Jun, the value is about $780.
If 穷小子 had hold his shares until now, and with the exercise of the rights shares:
The total value for the 6,000 shares will be valued at $1,104 based on the today's closed price at $0.184, and not forgetting to deduct $330 from this for the purchasing of the rights shares, which gives about $774.
Okie, no much difference in value, only $6. The few hundreds actually makes no much differences from the 88% lost anyway.
As mentioned in the previous post, it is not the dollar which made the sell call, but is more on the trust and confidence in this company.
With the sudden departure of the CEO's and its founder, it's just doesn't feel comfortable with purchasing the rights, and especially with the reason of having the company's intention to used it for repaying the debts. All these doesn't sum up as a good choice.
Not mentioning about the Minimum Trade Price rules, how will Noble tackle it? From the way 穷小子 sees it is either do a share consolidation or delist it from SGX, unless the managing board have new tricks under their sleeves.
It may continue its downwards trend from where it is currently. This shall be the last post regarding to Noble. Have decided to remove this from my watchlist. I don't see the point of keeping track of this any further, unless its fundamentals have changed.
On the side track, 穷小子 managed to have some profits from the Euro. Hehe.
Wednesday, 15 June 2016
OCBC scrip dividend received today
This is a review post about OCBC Scrip dividend Scheme.
100 of OCBC shares from the payment of Scrip dividend was credited to 穷小子's CDP account today. Including this, it would be the third time 穷小子 had opted for Scrip Dividend Scheme.
The decision made in May to opt for shares has been right so far.
To recap, the scrip dividend price is $8.11, the price which is after the 10% discount from the determined price at $9.01.
If 穷小子 have opted for Cash dividend instead, he would have received $810.18 only, rather than the value of $845.00 today. Although it seems to be a difference of $34.82 only, it is actually an additional of 4.29%.
Moreover, this 100 of OCBC shares will be included in the formula for computing the next scrip dividend which usually falls on August, about two months from now on. Let it Grow! Let it Grow!
The power of Scrip dividend and Compounding effects.

100 of OCBC shares from the payment of Scrip dividend was credited to 穷小子's CDP account today. Including this, it would be the third time 穷小子 had opted for Scrip Dividend Scheme.
The decision made in May to opt for shares has been right so far.
To recap, the scrip dividend price is $8.11, the price which is after the 10% discount from the determined price at $9.01.
Dividend Announced
|
$0.18 per share
|
Cash dividend value
|
$810.18
|
Amount of shares received via Scrip Dividend
|
100
|
Determined Price for Scrip Dividend (after 10% discount)
|
$8.11
|
Scrip Dividend Price as of 28 Apr 2016
|
$811.00
|
Last Closed Price
|
$8.45
|
Scrip Dividend Price as of today
|
$845.00
|
 |
| For anyone who needs the events timeline information |
Moreover, this 100 of OCBC shares will be included in the formula for computing the next scrip dividend which usually falls on August, about two months from now on. Let it Grow! Let it Grow!
The power of Scrip dividend and Compounding effects.

Wednesday, 25 May 2016
Frasers Centrepoint Limited - Will it gets better with the opening of Waterway Point and Safra Punggol?
Frasers Centrepoint Limited (FCL) was never in my watchlist until I visited Punggol Waterway Point. Most of the malls are managed by Frasers Centrepoint Trust (FCT), who is listed in Singapore Exchange too. *Do not confused between these two.*
I don't stay at Punggol, but I would go that area about 3 - 4 times each month. There are a lot of new HDB BTO around the area in the recent years, but it is not crowded, at least at Punggol station.
Waterway Point
With the opening of Waterway Point in Jan 2016, the game changes. Suddenly there is a surge in crowds. From what I can see, Punggol resident are hungry for shopping malls. Waterway Point reported that have it has 90% of tenants occupancy for its soft launch, with major anchor tenants such as NTUC Fair Price Finest (24 hours) and Shaw. Not only that, it has Timezone arcade for the kids, variety of cafes and restaurants (which is always long queue) for the teens, adults and families. I can say that it just have all the magnets to attracts the residents from all walks, and of course Daiso, 穷小子 style favourite.
To add on, managed to get Shaw as its tenant is one of the great move by the Frasers Management.
Based on the MRT North East Line, the only one cinema from Punggol to Serangoon is at NEX, Serangoon shopping mall, before the opening of Shaw at Waterway point. I used to stay at Hougang, the residents from the area are hoping for a cinema.
Safra Punggol
Furthermore with the opening of Safra Punggol at Apr 2016, which is less than 1KM away from Waterway Point, adds another plus factor to FCL. Safra Punggol is a different concept from the rest of SAFRA, as it is the first eco-friendly SAFRA club. I can see that the audience which its targeting are mainly young couples and kids, the Splash@Kidz Amaze indoor water playground answers it all. The first three-storey indoor water playground will not only attracts Punggol residents, but also from the whole of Singapore. I went there during the first weekend since it launched, the crowd for the pool was crazy, all the time slots for entry were fully booked till it closed.
I do not know whether my observations would means the stock price will increase, but what I can say is that all of these are plus factors which will bring in crowds, and these are certainly benefits to FCL. Another financial factor is that the price is currently at an estimated of 0.60 of its book value only based on today closing price. In layman term means the price is discounted.
Except that I don't like its high debt ratio and the low liquidity in the stock exchange, other than that, FCL is not bad for a thought.
By the way, I'm not vested in this yet, still waiting for an opportunity. News of US interest rate hike may bring the price down for a good catch. Who knows.

Thursday, 12 May 2016
OCBC Scrip Dividend Scheme
After waited for more than 2 weeks since XD date, have received the letter of notice for my scrip dividends from OCBC today. Finally.
What is scrip dividend?
Investopedia: A stock dividend is a dividend payment made in the form of additional shares, rather than a cash payout.
穷小子: Basically is payment to you by shares instead of cash for dividends.
From what I know, the 3 local pillar banks (DBS, OCBC, UOB) stocks may give their shareholders an option to choose between payment by shares or cash for each round of dividends payment. No, scrip dividend is not a mandatory for every year, it is a decision by the management and is one of the resolutions which the shareholders had to vote during the Annual General Meeting. In short, we wouldn't know whether the company would still have scrip dividend for next year until the next AGM.
How is the number of OCBC shares determined?
There is a formula for this actually. Using the amount of dividend (cash) which supposed to receive, divided by a 10% discount to the price which was determined during the price determination period, from 26 April 2016 to 28 April 2016 (both dates inclusive).
The price was determined at $9.01 for this round of dividend. which gives you a $8.11 after the 10% discount.
E.g. Supposing should you received $405.50 as cash dividend, you will have entitlement of 50 OCBC shares as scrip dividend scheme.
Should take up scrip dividend or cash dividend?
Let's weight some of the pros and cons which I can think of now if choose to receive in scrip dividend.
Pros
Errmm. One more Pros pointers for 穷小子. He was entitled 100 shares for this round of scrip dividend, no odd lots for this time.

What is scrip dividend?
Investopedia: A stock dividend is a dividend payment made in the form of additional shares, rather than a cash payout.
穷小子: Basically is payment to you by shares instead of cash for dividends.
From what I know, the 3 local pillar banks (DBS, OCBC, UOB) stocks may give their shareholders an option to choose between payment by shares or cash for each round of dividends payment. No, scrip dividend is not a mandatory for every year, it is a decision by the management and is one of the resolutions which the shareholders had to vote during the Annual General Meeting. In short, we wouldn't know whether the company would still have scrip dividend for next year until the next AGM.
How is the number of OCBC shares determined?
There is a formula for this actually. Using the amount of dividend (cash) which supposed to receive, divided by a 10% discount to the price which was determined during the price determination period, from 26 April 2016 to 28 April 2016 (both dates inclusive).
The price was determined at $9.01 for this round of dividend. which gives you a $8.11 after the 10% discount.
E.g. Supposing should you received $405.50 as cash dividend, you will have entitlement of 50 OCBC shares as scrip dividend scheme.
Should take up scrip dividend or cash dividend?
Let's weight some of the pros and cons which I can think of now if choose to receive in scrip dividend.
Pros
- The determined price is still lower than the market price, which is $8.33 as of today closed price.
- Although it became less than 2.5% discount instead of the 10% discount, we still had a free $0.22 per share from the scrip.
- Fractional entitlements to a hundredth of a share or more will be rounded up to the nearest whole share. E.g.
- 50.01 shares will be rounded up to 51,
- 50.009 shares will be rounded down to 50 shares. - Is a good method for compounding if you are looking it as a long term investment.
- Saves all the commissions and fees for the buying and selling transactions if one chooses to reinvest the dividend.
- The value of the shares from the scrip dividends may increase in future. So long the price is more than $8.11, it means is in paper profits already.
Cons
- No cash received, means no actual gain realised. Cash is King, some may say.
- It may no longer to be seen as a 10% discount, because of the market price is getting nearer to $8.11. Might as well take the cash first and plan for the next move.
- There will be odd lots in resulted, which may be inconvenient to sell in the market.
- The value of the shares from the scrip dividends may decrease in future. If the market price is less than $8.11, it is "eating" up the dividends, which means is in paper loss.
Scrip dividend or Cash dividend? You make the call.
This is the third time which I will opt for scrip dividend. Okie, I am bias, I can't think of much cons for this. It is a brown form this time instead of the green form which were received previously. Maybe because I had made a standing instruction for receiving scrip dividend as my permanent election for all my subsequent dividends until further notice.Errmm. One more Pros pointers for 穷小子. He was entitled 100 shares for this round of scrip dividend, no odd lots for this time.

Subscribe to:
Posts (Atom)